Strategy’s latest report delivered one of the largest-ever quarterly losses, with the Bitcoin treasury company booking a net loss of $8.22 billion in Q2 2026, reversing a profit of more than $10 billion a year ago.

The primary reason for the decrease was not an $8.2 billion cash outflow but, rather, an accounting loss on Bitcoin. Thus, Strategy’s Q2 results test the market’s understanding of “fair-value” accounting and the willingness to fund the capital structure envisioned by Michael Saylor.
Read more: Is Michael Saylor Losing Faith in Bitcoin? Strategy Sells 3,588 BTC Worth $226M
Contents
Why Strategy Reported An $8.2 Billion Q2 Loss
The Bitcoin Price Decline Behind The Non-Cash Accounting Loss
The main culprit behind Strategy’s Q2 loss was an unrealized decline in digital assets of around $8.32 billion. The sharp drop in Bitcoin’s price reduced the quarter-end value of Strategy’s bitcoin holdings, which had been recorded at fair value.
Most of the losses were non-cash since the company had not sold any of its Bitcoins. Still, the accounting charges eroded the value of the shares and increased the volatility of the stock. The stock is inherently tied to Bitcoin’s performance.
Fair-Value Accounting: Why Paper Losses Hit Earnings So Hard
Under fair-value accounting rules, Strategy’s BTC▲$77,666.00 had to be marked to the lower prices at the end of the quarter. Thus, a rise in Bitcoin’s value generates profits for the treasury firm, while a decline causes losses.
Therefore, while revenue from software sales grew, contributing to the overall profit, investors need to analyse the BTC position when studying Strategy’s earnings report. In particular, mark-to-market accounting provides a fair valuation of the firm’s Bitcoin, but it decreases the value of shares and makes EPS comparisons difficult.
Revenue, EPS And Key Q2 2026 Financial Highlights
The Bitcoin company’s revenue for the June 2026 quarter was $122.4 million, up 6.9% year over year. Gross profit reached $81.6 million with a healthy 66.6% margin. The software segment was steady, but it contributed little to overall revenue.
The company’s operating income was $8.33 billion, net loss was $8.22 billion, while the EPS was negative $24.45. Net loss attributable to common stockholders reached $8.62 billion, which follows the dilution from preferred stock dividends of approximately $400.7 million. With respect to MSTR, Bitcoin’s valuation and funding costs are much more important than revenue and EPS.
Is Michael Saylor Really In Crisis?
Why The Headline Loss Doesn’t Tell The Whole Story
Even though Michael Saylor’s company posted a sizeable loss, the bitcoin treasury firm spent or invested about $8.2 billion. The main reason for the pain was a lower BTC price at the end of the quarter, and Strategy did not sell the vast majority of its holdings. Nevertheless, it would be unwise to ignore the importance of the accounting loss.
In particular, the Bitcoin spot price is not the only important number for Strategy since the company needs to fund its operations, pay interest on debt, and distribute preferred dividends. Therefore, while the 8-figure decline in the value of bitcoins on paper is significant, the real test will be whether Saylor’s Strategy can maintain its liquidity and access to capital when Bitcoin falls, and the premium over its shares narrows.
Read more: Saylor’s Strategy Is Cracking — Industry Figures Say the Bitcoin Model Has Run Its Course
Strategy Still Holds Over 843,000 BTC Despite Market Pressure
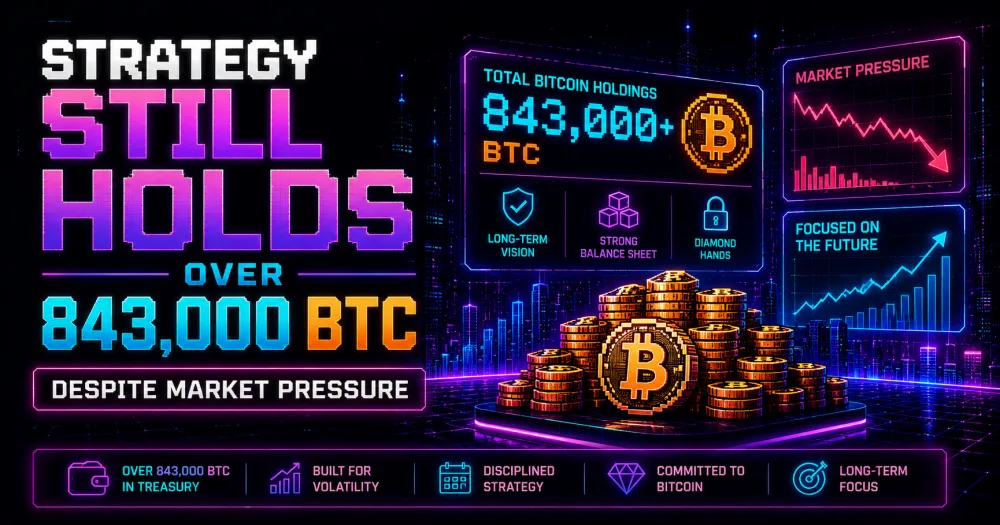
As of June 30, the Bitcoin company held 846,000 BTC, and 843,775 BTC as of July 26, after selling about 3,588 BTC in early July. The latter number represents only 0.4% of the company’s bitcoin holdings as of the beginning of the month. As of July 26, the cost basis of each bitcoin held by Strategy was approximately $63.69 billion and an average acquisition price near $75,476; according to a reference price of $64,915, it was worth approximately $54.77 billion.
Thus, the numbers highlight the scale of the Michael Saylor Bitcoin position, which remains the largest among institutional investors. At the same time, the value of the portfolio was below the cost basis at the reference price as of the end of July.
Bitcoin Yield And Other Metrics Management Wants Investors To Watch
Management highlighted a 4.5% year-to-date BTC Yield, a BTC Gain of 29,997, and an illustrative BTC Dollar Gain of $1.95 billion. Bitcoin Yield, according to Strategy, is calculated using the Bitcoin change held per diluted share.
It is important to note that Bitcoin Yield is not a measure of income, cash, or return on investment, but rather it is a method to track the accumulation of bitcoin per share. Thus, the company can report a positive yield and a large net loss at the same time.
In particular, as mentioned above, Strategy can record a yield if it accumulates bitcoin, even if the price of cryptocurrency declines. Nevertheless, the metric does not account for preferred shares, debt, liquidity costs, or the price of MSTR shares compared to the yield on bitcoin.
Strategy’s Biggest Shift: Selling Bitcoin Instead Of Only Buying
Why the Company Sold 3,588 BTC In July
The number 3,588 BTC represents the number of bitcoins sold by the company in early July, between June 29 and July 5. Thus, the actual number of Bitcoin sold in early July was only 2,225 BTC. In addition, the company sold 1,363 BTC in the last two days of June and generated proceeds of about $216 million in total.
The Bitcoin company’s BTC sale in early July represented a small fraction of its overall holdings but marked a significant shift in its accounting policy and a change in the narrative around the stock. In particular, Strategy sold Bitcoin for the first time in its history in late June and early July, signaling that the cryptocurrency could serve as a liquid asset to fund operations.
Funding Preferred Stock Dividends And Building A Cash Reserve
The company’s early July Bitcoin sale was made to fund preferred stock dividends and build a cash reserve. In particular, as of late July, the dollar reserve reached $3.75 billion, covering more than two years’ worth of preferred dividends, interest, and other expenses. In addition, the company has authorized the monetization of up to $1.25 billion additional Bitcoins in early July.
Thus, the reserve reduction will ease liquidity pressures on the company while also serving as a useful hedge against further declines in the price of Bitcoin. Nevertheless, it is essential to remember that preferred shares play a critical role in the capital structure of Strategy.
Does This Mark the End Of the “Never Sell” Narrative?
Even though the bitcoin company continued to acquire the cryptocurrency, early July sales marked the end of the “never sell” policy and demonstrated a realistic understanding of its financial needs and risks. In particular, management has acknowledged the importance of accumulating bitcoins while also considering the need to sell to generate cash to cover dividends, interest, and other expenses.
Therefore, while the new approach allows Strategy to purchase more bitcoins, it will reduce the growth of the shares since preferred stock dividends and other costs will reduce the value of the shares.
Investors Are Asking a Bigger Question: Is Strategy’s Capital Model Breaking?
How mNAV Compression Changed the Investment Thesis
The mNAV (modified net asset value) of Strategy reflects the value of the company’s shares in relation to the value of its bitcoins and other assets. Particular interest is represented by the ratio of the price of MSTR shares to the mNAV, which, as of early July, was 1.0.
A price above 1.0 indicates that Strategy’s shares are trading at a discount to the value of the company’s bitcoins, which allows it to buy more bitcoins and generate additional profits. On the other hand, as mNAV approaches 1.0, the capitalization capability of the company decreases, and the value of shares decreases.
There are two reasons for this, namely, the issuance of new shares of common stock and the increase in the value of shares of preferred stock. The former reduces the number of bitcoins purchased per share of common stock, while the latter reduces the value of the shares of preferred stock. Thus, in the context of the decline in the value of bitcoins, the compression of mNAV will allow Strategy to buy less Bitcoin.
Why Preferred Shares And Dividends Are Now Central to the Story
Preferred shares of STRC give shareholders a higher priority over common shares. In addition, preferred shareholders are entitled to receive dividends. As for STRC dividends, they have increased to 12% in early July, and the company began buying back its preferred shares at prices below the $100 face value.
In particular, Strategy purchased about $28.9 million of stated value for roughly $25 million in STRC shares between July 20 and July 26. In addition, the company authorized a $1 billion share repurchase program for MSTR, although no shares had been repurchased as of the date of the report. In other words, the allocation of capital to shareholders has become more important for Strategy, and preferred shares have taken priority over common shares.
Related: Who Is Michael Saylor and Why He’s Betting Billions on Bitcoin
What Analysts See As the Biggest Risks Going Forward
The first risk is the further decline in the price of Bitcoin. The second risk is the compression of mNAV, and the third risk is the growth in preferred dividends, interest, and other expenses. In addition, several other concerns include dilution, the need for refinancing, insufficient demand for new shares, and further sales of Bitcoin.
Thus, the capitalization model of Strategy is not necessarily flawed, but it has become a multi-faceted risk management issue.
How Did the Market React?
MSTR Stock Performance After Earnings
MSTR closed at nearly $97.74 per share at the end of the day, and it dropped slightly after the close of trade. In other words, the wild swings in the price of bitcoin were largely discounted by the market. In particular, Strategy announced early July Bitcoin sales, and the entire MSTR story was known to market participants before the release of the earnings report.
Therefore, investors were not surprised by the loss and focused primarily on whether the Bitcoin company would be able to restore the value of its shares over the value of its Bitcoins, that is, the premium.
Bitcoin’s Reaction And Broader Crypto Market Sentiment
Bitcoin remained within the tight range of $60,000 at the end of the week. More broadly, the market’s perception of crypto was generally weak and volatile.
The sale of 3,588 BTC was relatively small, and it could not have had a significant impact on the price of Bitcoin. Nevertheless, the fact that the world’s largest treasury company sold Bitcoin was no less important.
In particular, some market analysts felt that it was an excellent move to hedge against further declines in the price of Bitcoin, while others believed that Strategy had weakened the entire system by creating another mechanism for diluting shares.
What Wall Street Expected Versus What Strategy Delivered
The company’s software sales were relatively close to street expectations, and the main disappointment was the loss of $24.45 per share, which was much higher than expected. At the same time, EPS figures are highly dependent on the price of Bitcoin at the end of the quarter.
Thus, Strategy delivered more shares of preferred stock, a lower amount of convertible debt, and the ability to raise more funds in the capital markets. On the other hand, the company posted a large account loss, an increase in preferred dividends, and uncertainty about future Bitcoin purchases.
What Comes Next For Strategy And Bitcoin?
Will Strategy Resume Aggressive BTC Purchases?
Aggressive BTC buying could resume if the price of Bitcoin rises, the premium over mNAV grows, and the demand for preferred stock increases. The company raised about $8.41 billion through at-the-market programs during Q2 and another $1.28 billion in shares of preferred stock through July 26.
Nevertheless, management has several priorities, including maintaining a reserve, buying shares of preferred stock, and paying off debt. Therefore, while Strategy will continue to purchase Bitcoins, these transactions are unlikely to be aggressive.
Could Another Bitcoin Rally Quickly Reverse Accounting Losses?
Another rally in the price of Bitcoin would allow the company to offset some of the losses related to the write-down of its BTC. In other words, the rally in Bitcoin will help Strategy’s EPS, since the value of Bitcoins will increase on paper.
Under fair-value accounting, a rally in Bitcoin’s price before the end of the quarter will result in an unrealized gain, which will increase the value of Strategy’s shares. In particular, with a Bitcoin position of 843,775, every $10,000 increase in Bitcoin’s price adds roughly $8.4 billion to the value of the portfolio before taxes and other liabilities will contribute to EPS.
Nevertheless, a rally in the BTC price will be insufficient to offset the losses for preferred shareholders, who will continue to fund Strategy in exchange for shares and dividends. Thus, despite the importance of the price of Bitcoin, the capital structure of the company determines the value of its shares.
Key Catalysts Investors Should Watch in Q3 2026
The key catalyst for investors in the third quarter of 2026 will be the price of Bitcoin on September 30. In particular, it will determine the next set of unrealized gains or losses, and it is crucial for the MSTR share price.
Other catalysts should be seen as mNAV, new issuance of MSTR shares, the purchase or sale of bitcoins, the size of the reserve in USD, and the movement of STRC shares towards parity with par.
In addition, investors should watch out for changes in preferred dividends, share repurchases, reductions in convertible debt, and changes in the number of bitcoins per share. Strategy’s Q2 2026 results indicate that the model works, but liquidity and funding costs are now much more important factors than the price of Bitcoin.
FAQ
Why Did Strategy Report an $8.2 Billion Q2 Loss?
The reason for the loss was an unrealized decline in the value of Strategy’s investment in Bitcoin by approximately $8.32 billion. In turn, this led to accounting losses for the company.
How Much Bitcoin Does Strategy Hold?
As of July 26, the company held 843,775 BTC with an average cost basis of approximately $75,476 per Bitcoin.
Why Did Strategy Sell Bitcoin?
The company sold 3,588 BTC in early July to raise funds to finance preferred dividends. In addition, the company has taken steps to replenish its dollar reserve.
Is Strategy’s Bitcoin Model Breaking?
The model is at greater risk of failure due to a decrease in the Bitcoin price, a decrease in the value of shares of Strategy, and an increase in preferred dividends. Nevertheless, the company still has a substantial Bitcoin position and access to capital markets.
What Could Help MSTR Stock Recover?
A rally in the price of Bitcoin, an increase in the value of shares of Strategy, a decrease in preferred dividends, and a decrease in funding costs could help improve the value of MSTR shares.